J.P.Morgan Personal Investing | Product Design
Simplifying pension contributions for limited company directors
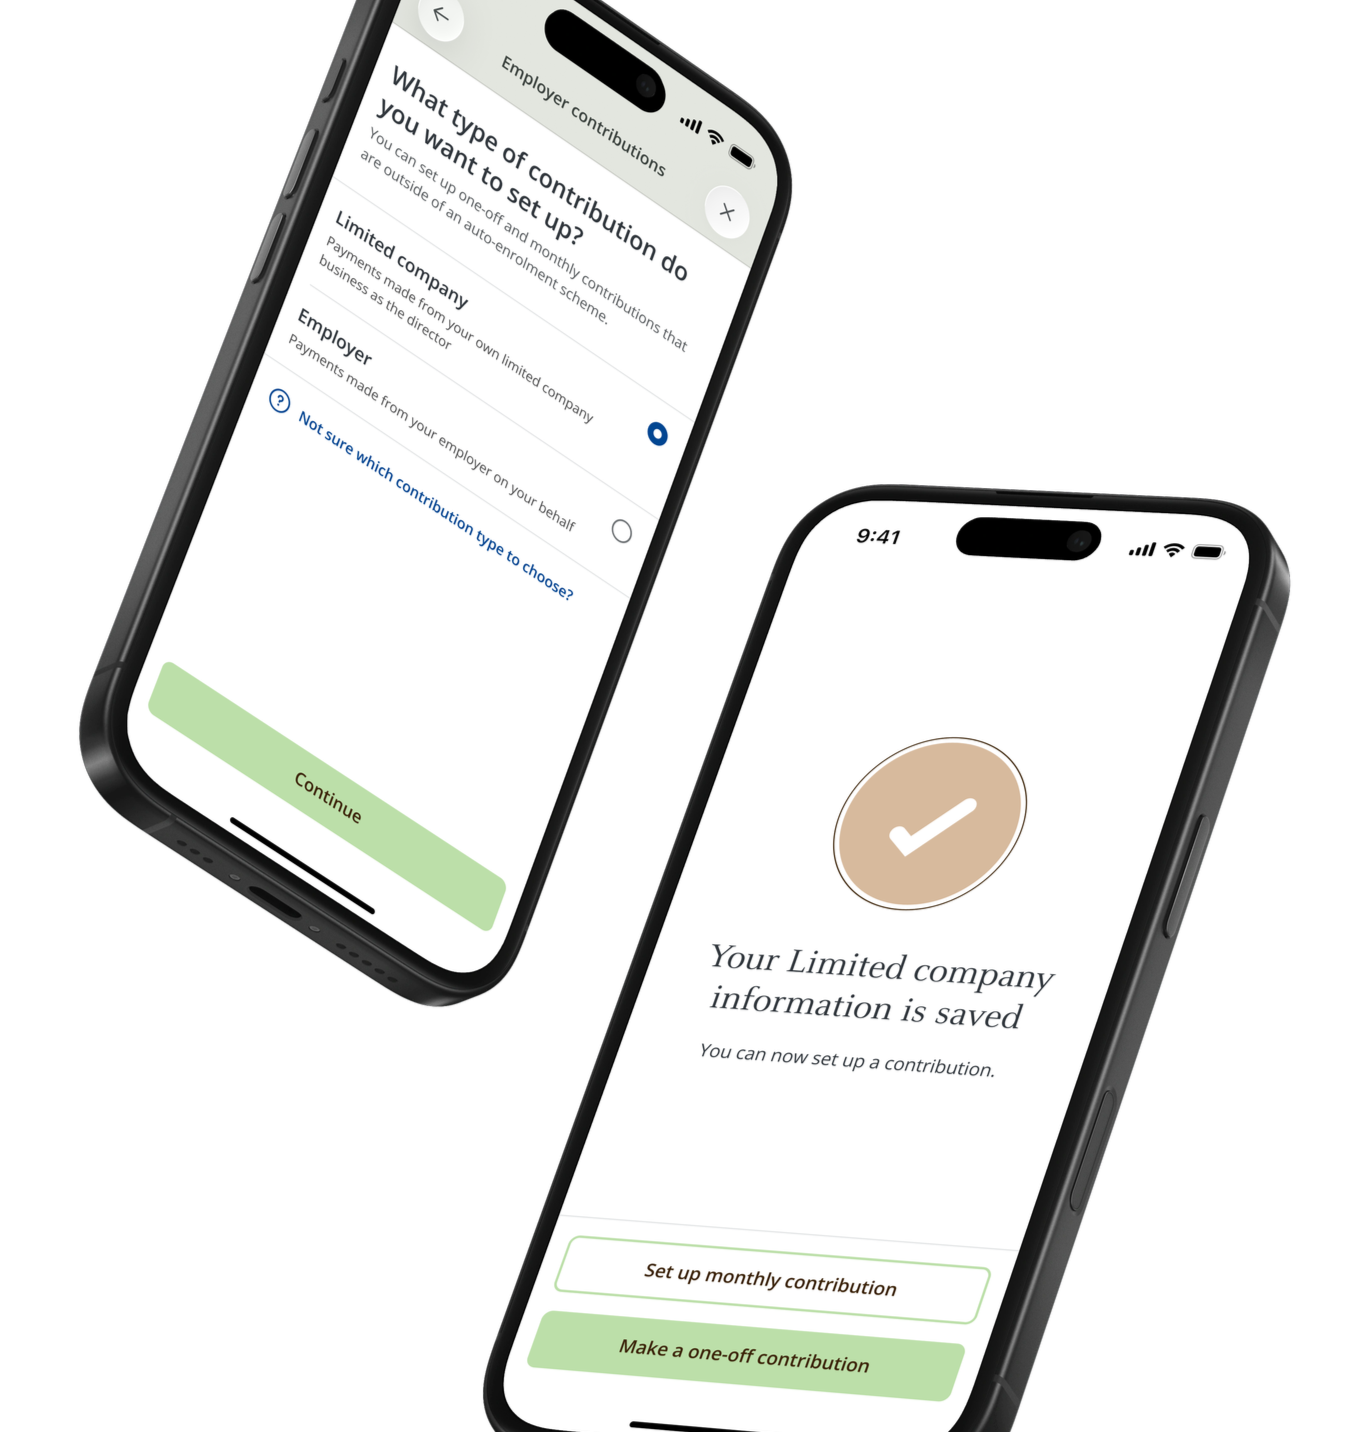
PROJECT CONTEXT
Our pension clients have the ability to set up employer contributions to their pension. However the existing employer contribution journey was designed around traditional employers, requiring clients to complete lengthy forms, wait 10–14 days for payments to arrive, and navigate limited flexibility to amend contributions once established.
This created friction for limited company directors making employer contributions into their own pensions — a group that now represents 75% of our pension client base. The project presented an opportunity to redesign the experience around their needs, creating a simpler, more flexible and intuitive journey tailored to how they manage their pension contributions.
THE ASK
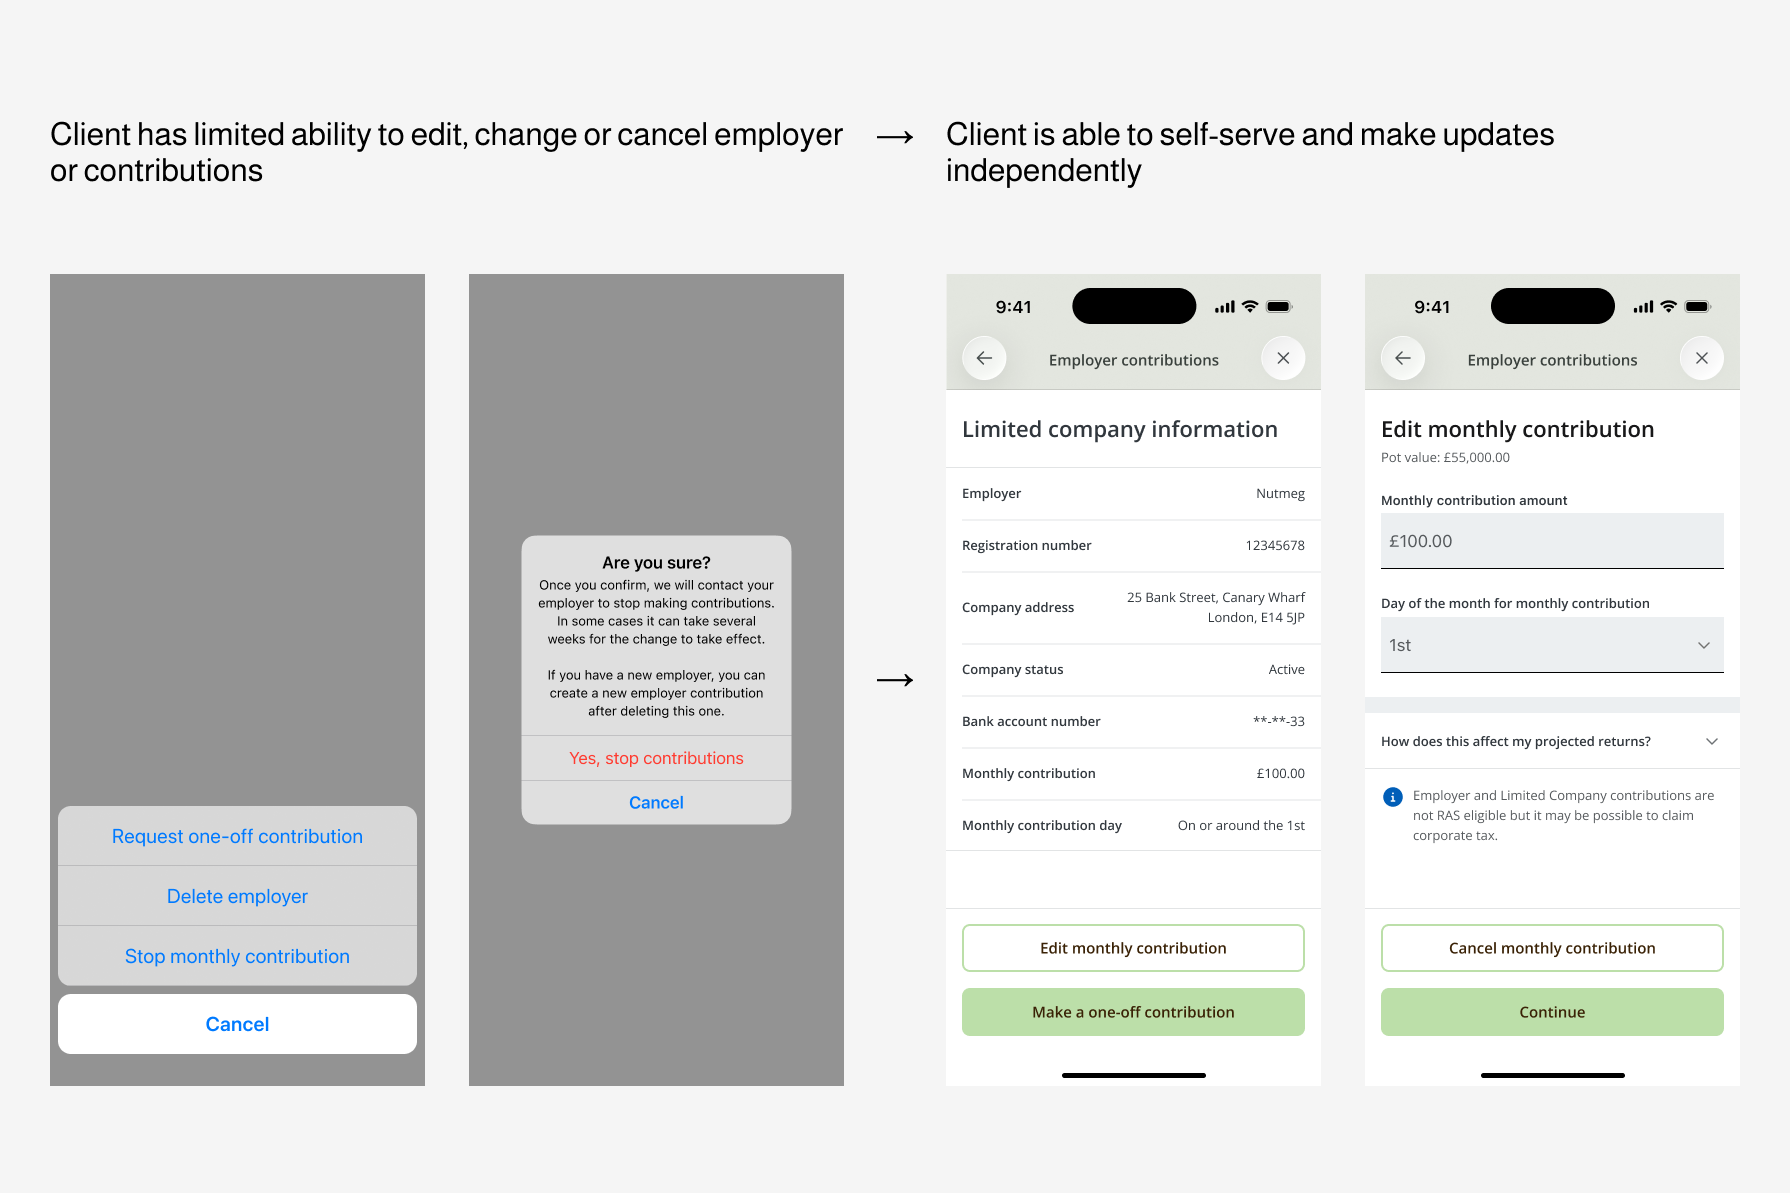
Create a dedicated contribution journey for limited company directors, enabling them to set up, edit and cancel contributions.
Simplify setup, reduce unnecessary steps and enable faster payments through familiar methods, while maintaining a clear distinction between limited company and traditional employer contributions.
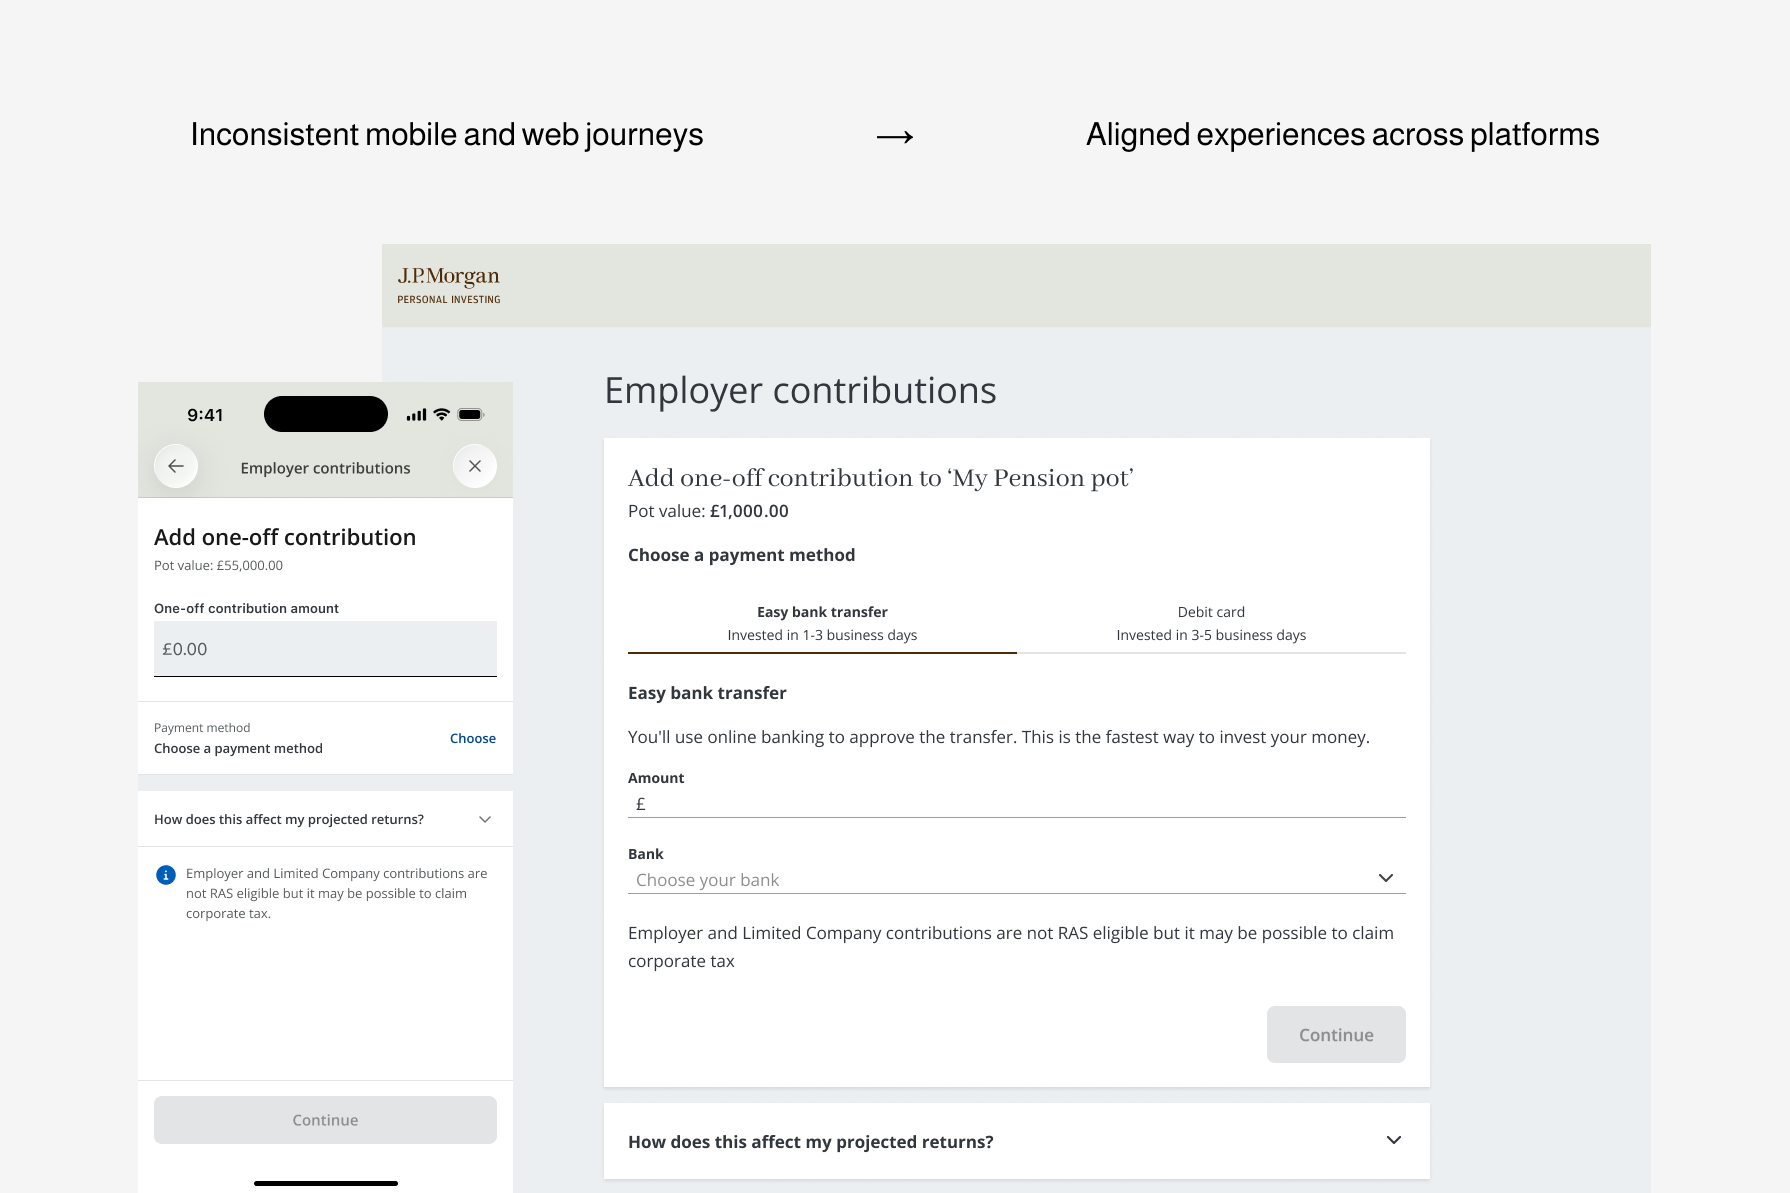
Align with industry standards and competitor offerings, while delivering a clear, intuitive experience across mobile and web.
MY ROLE
As Senior Product Designer, I led the end-to-end design process, from competitor analysis and user research through to journey design, approvals and delivery. Working closely with Product, Content, Research, Accessibility and Engineering teams, I identified key friction points, validated design decisions with customers and developed a streamlined, self-serve experience that balanced customer needs, business priorities and technical feasibility.
APPROACH & DISCOVERY
Rethinking the contribution experience
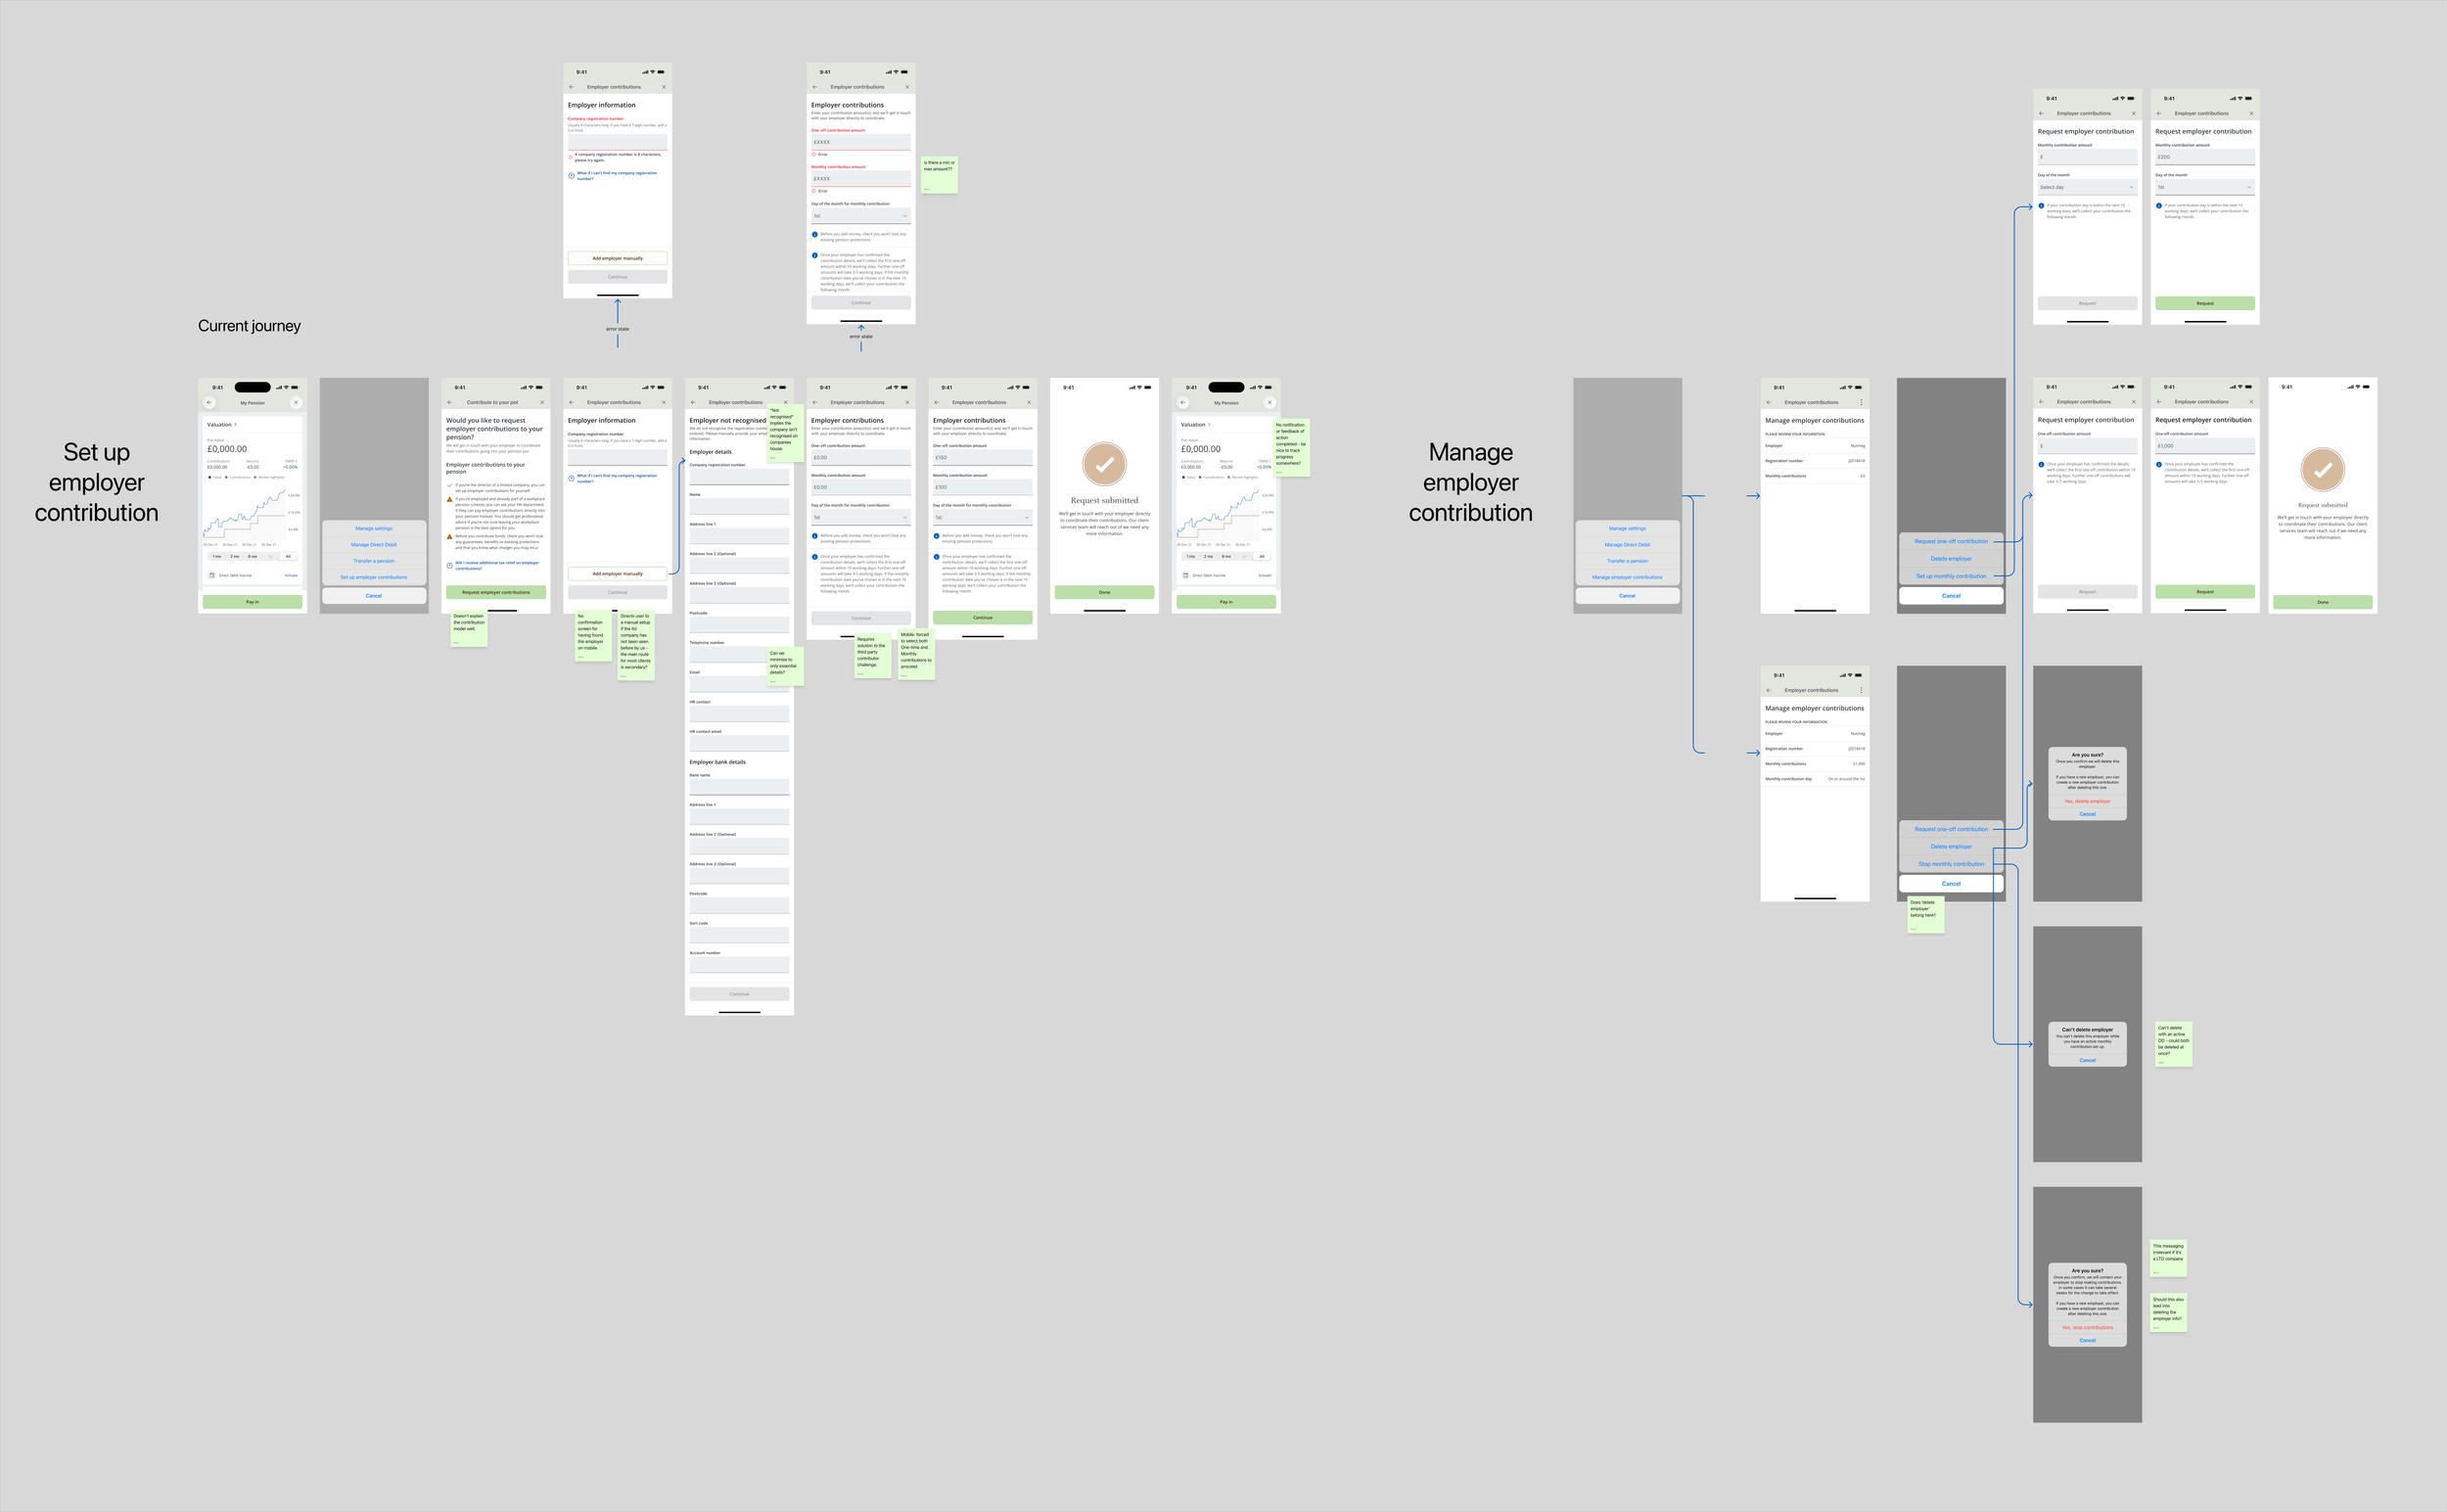
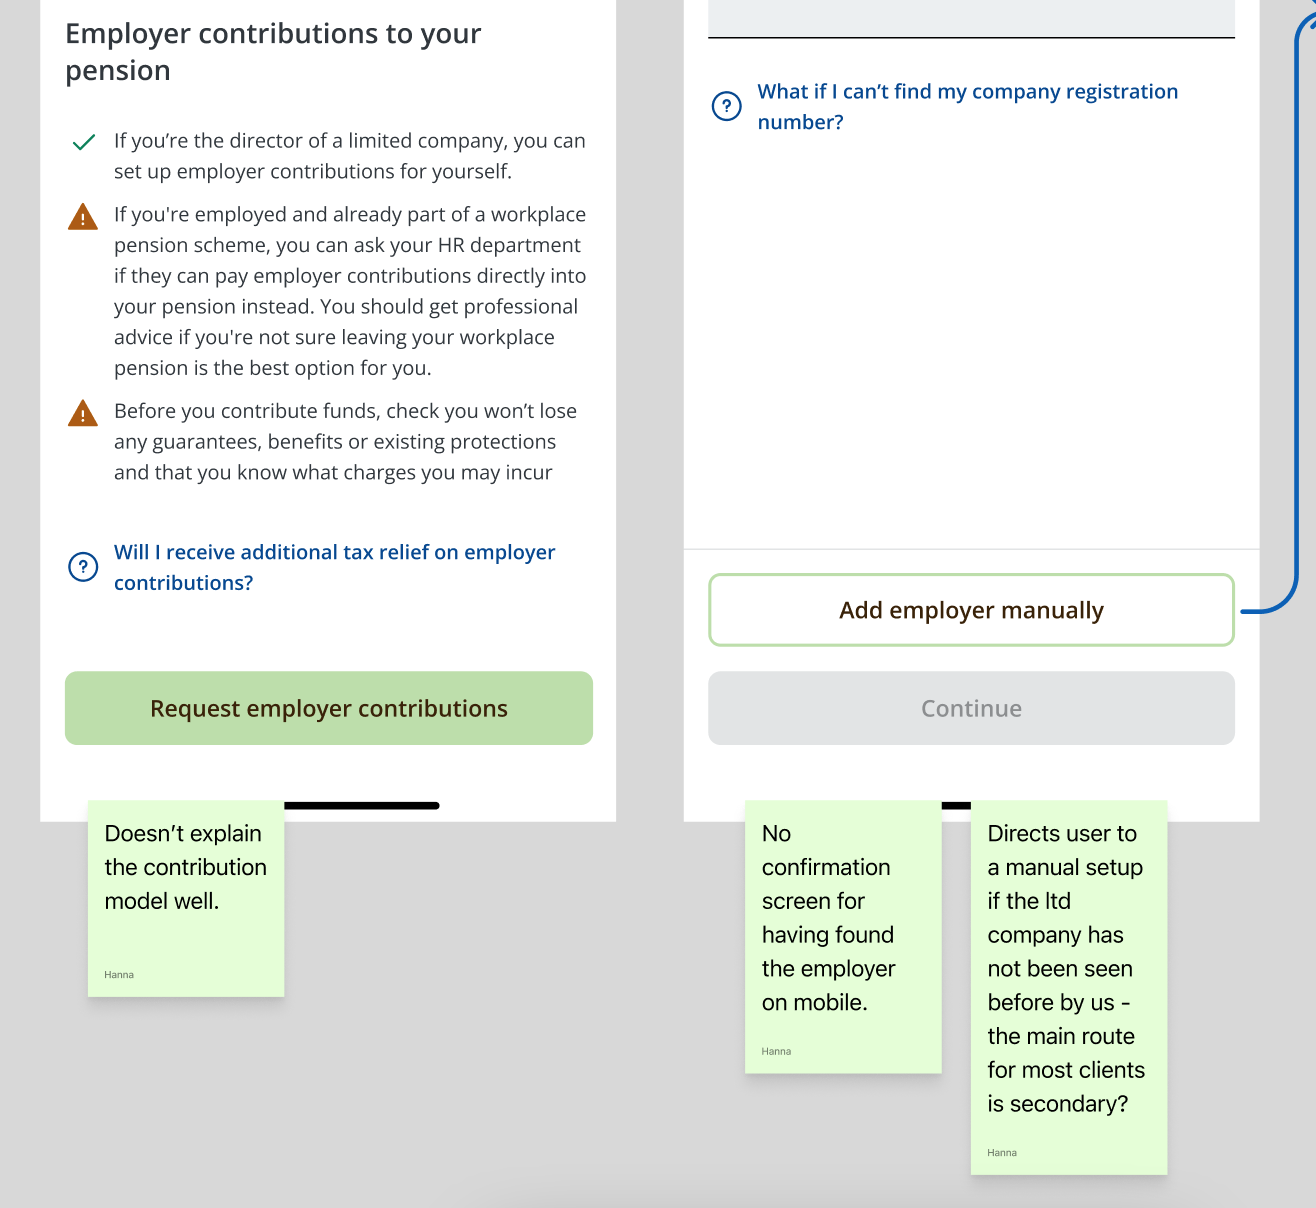
The existing pension contribution journey created unnecessary friction, with a convoluted setup process, excessive information requirements and limited transparency and tracking post submission.
Problems to solve:
Confirmation, transparency & excessive time to cash
Customers don't know if their employer contribution request was successfully received or is being processed, which sometimes leads to duplicate requests being submitted and double payments being made. Payments take 10-14 days to be set up causing significant friction for clients particularly in time sensitive tax year end situations.Process confusion & UX friction
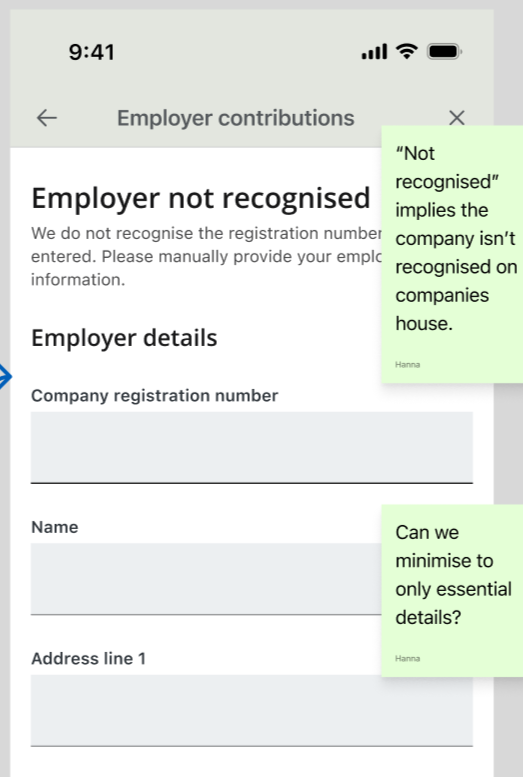
The contribution set up flow is convoluted, confusing, conflates contribution types, and forces unnecessary steps. The current flow forces these clients to input 20 data points in order to set up an employer, much of the information being unnecessary (e.g. company HR contact).Employer detail management & errors
Updating employer details is error-prone as some company information is locked, projections can be inaccurate as the employer may pay an amount different to what was requested, and clients can’t reliably stop/remove/change employers across states (e.g. when an active DD exists).
Understanding the competitor landscape
PensionBee, Penfold and MoneyBox are market leaders in their pension offering.
These competitors offer streamlined employer flows with minimal data capture and in some cases a live API call to Companies House to replay information, ensuring accurate data is captured and reassuring clients before they proceed.
They clearly signal and explain the different contribution types and payment methods offered - common options provided are open banking, manual bank transfer and direct debits.
RESEARCH & TESTING
Finding the right language and entry point
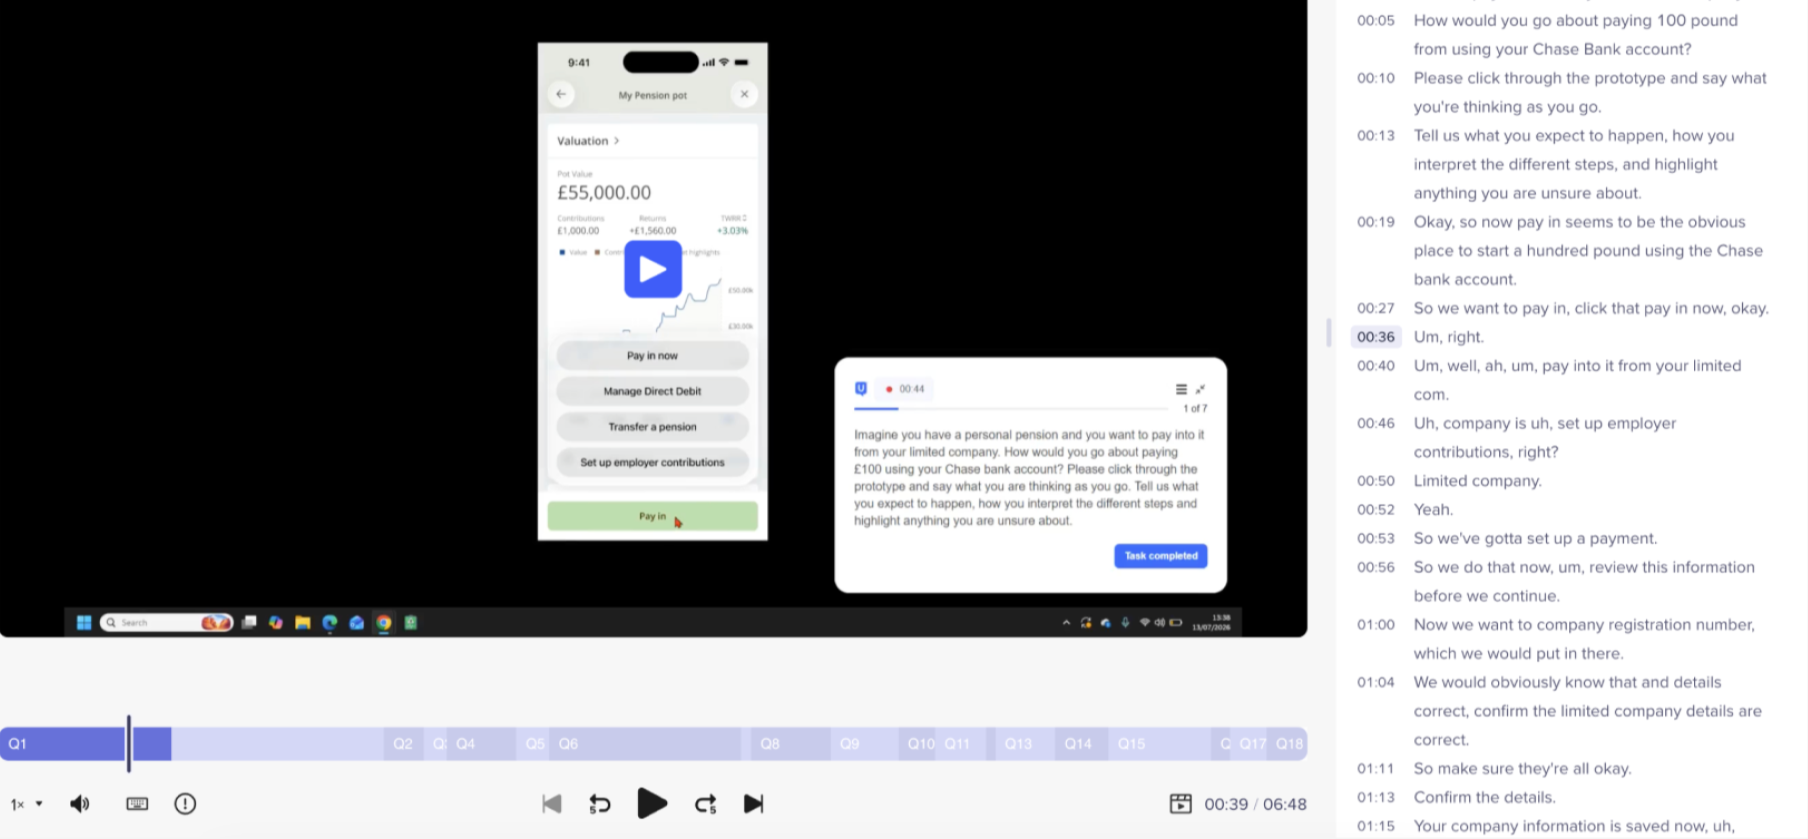
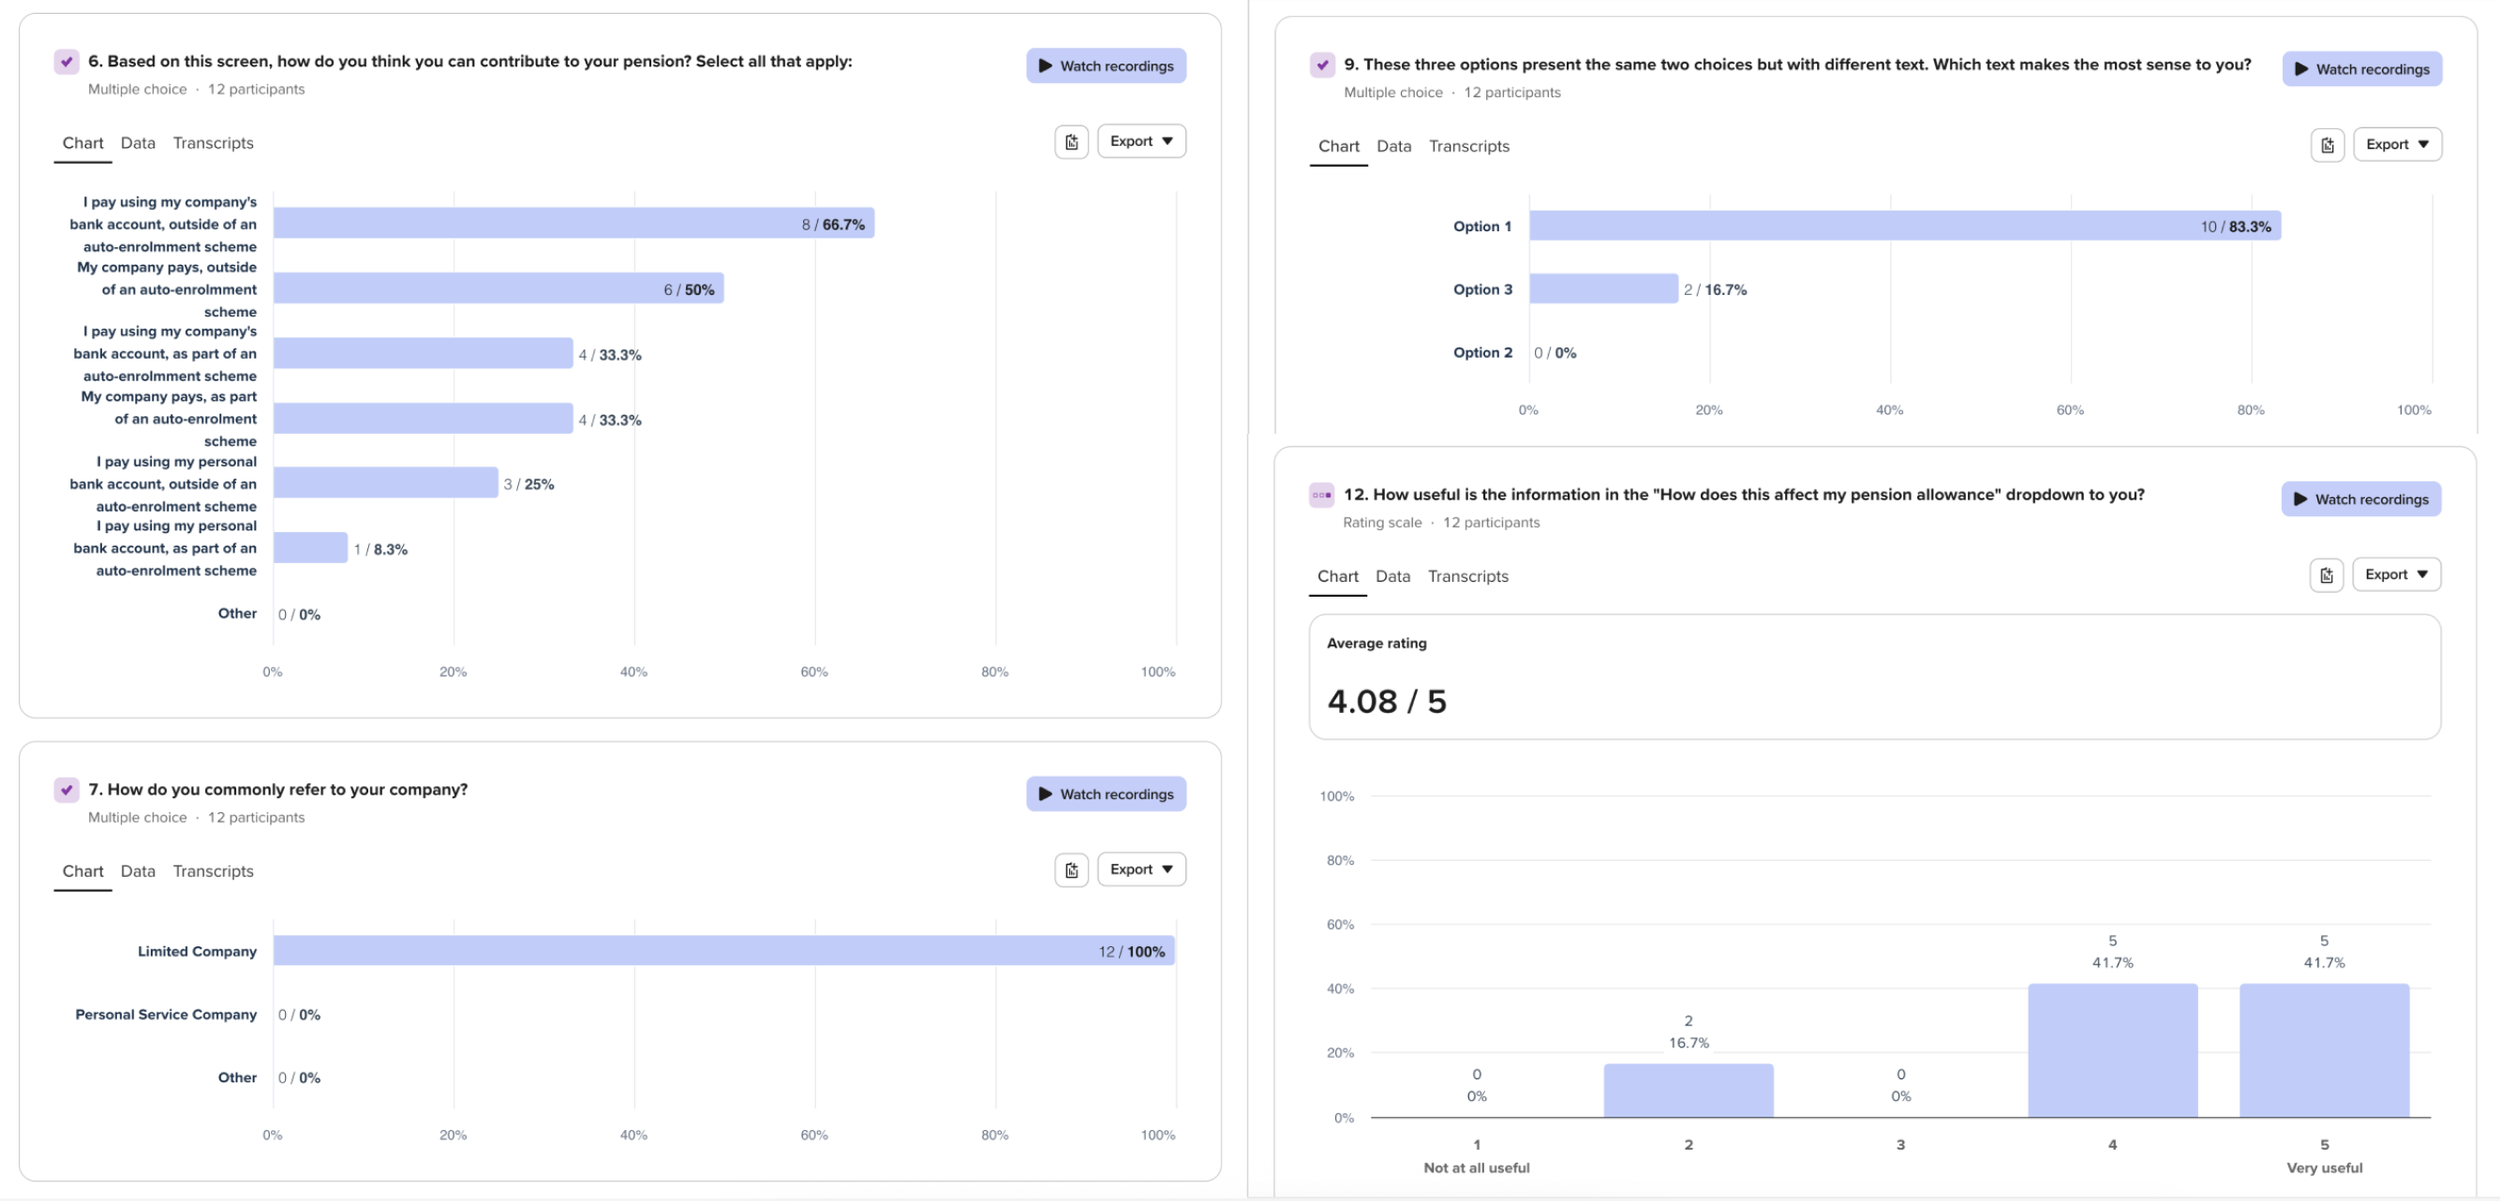
I conducted user research to understand how customers perceived employer and limited company contributions, testing different ways to communicate the distinction and help customers identify the right pathway.
Clarifying contribution types
Tested alternative terminology and messaging, discovering the importance of explicitly communicating that these contributions sat outside workplace auto-enrolment schemes.Testing discoverability
Explored whether employer contributions should sit within the main Pay In action. While this made the option easy to find, it introduced an irrelevant choice for the majority of pension customers, as only 20% make employer contributions.Balancing visibility with relevance
Used these findings to inform the decision to create a separate, dedicated entry point for employer contributions, keeping the primary Pay In journey focused on the needs of most customers.
The research helped shape both the language and information hierarchy of the experience, ensuring the new pathway was understandable and accessible without adding unnecessary complexity to the core journey.
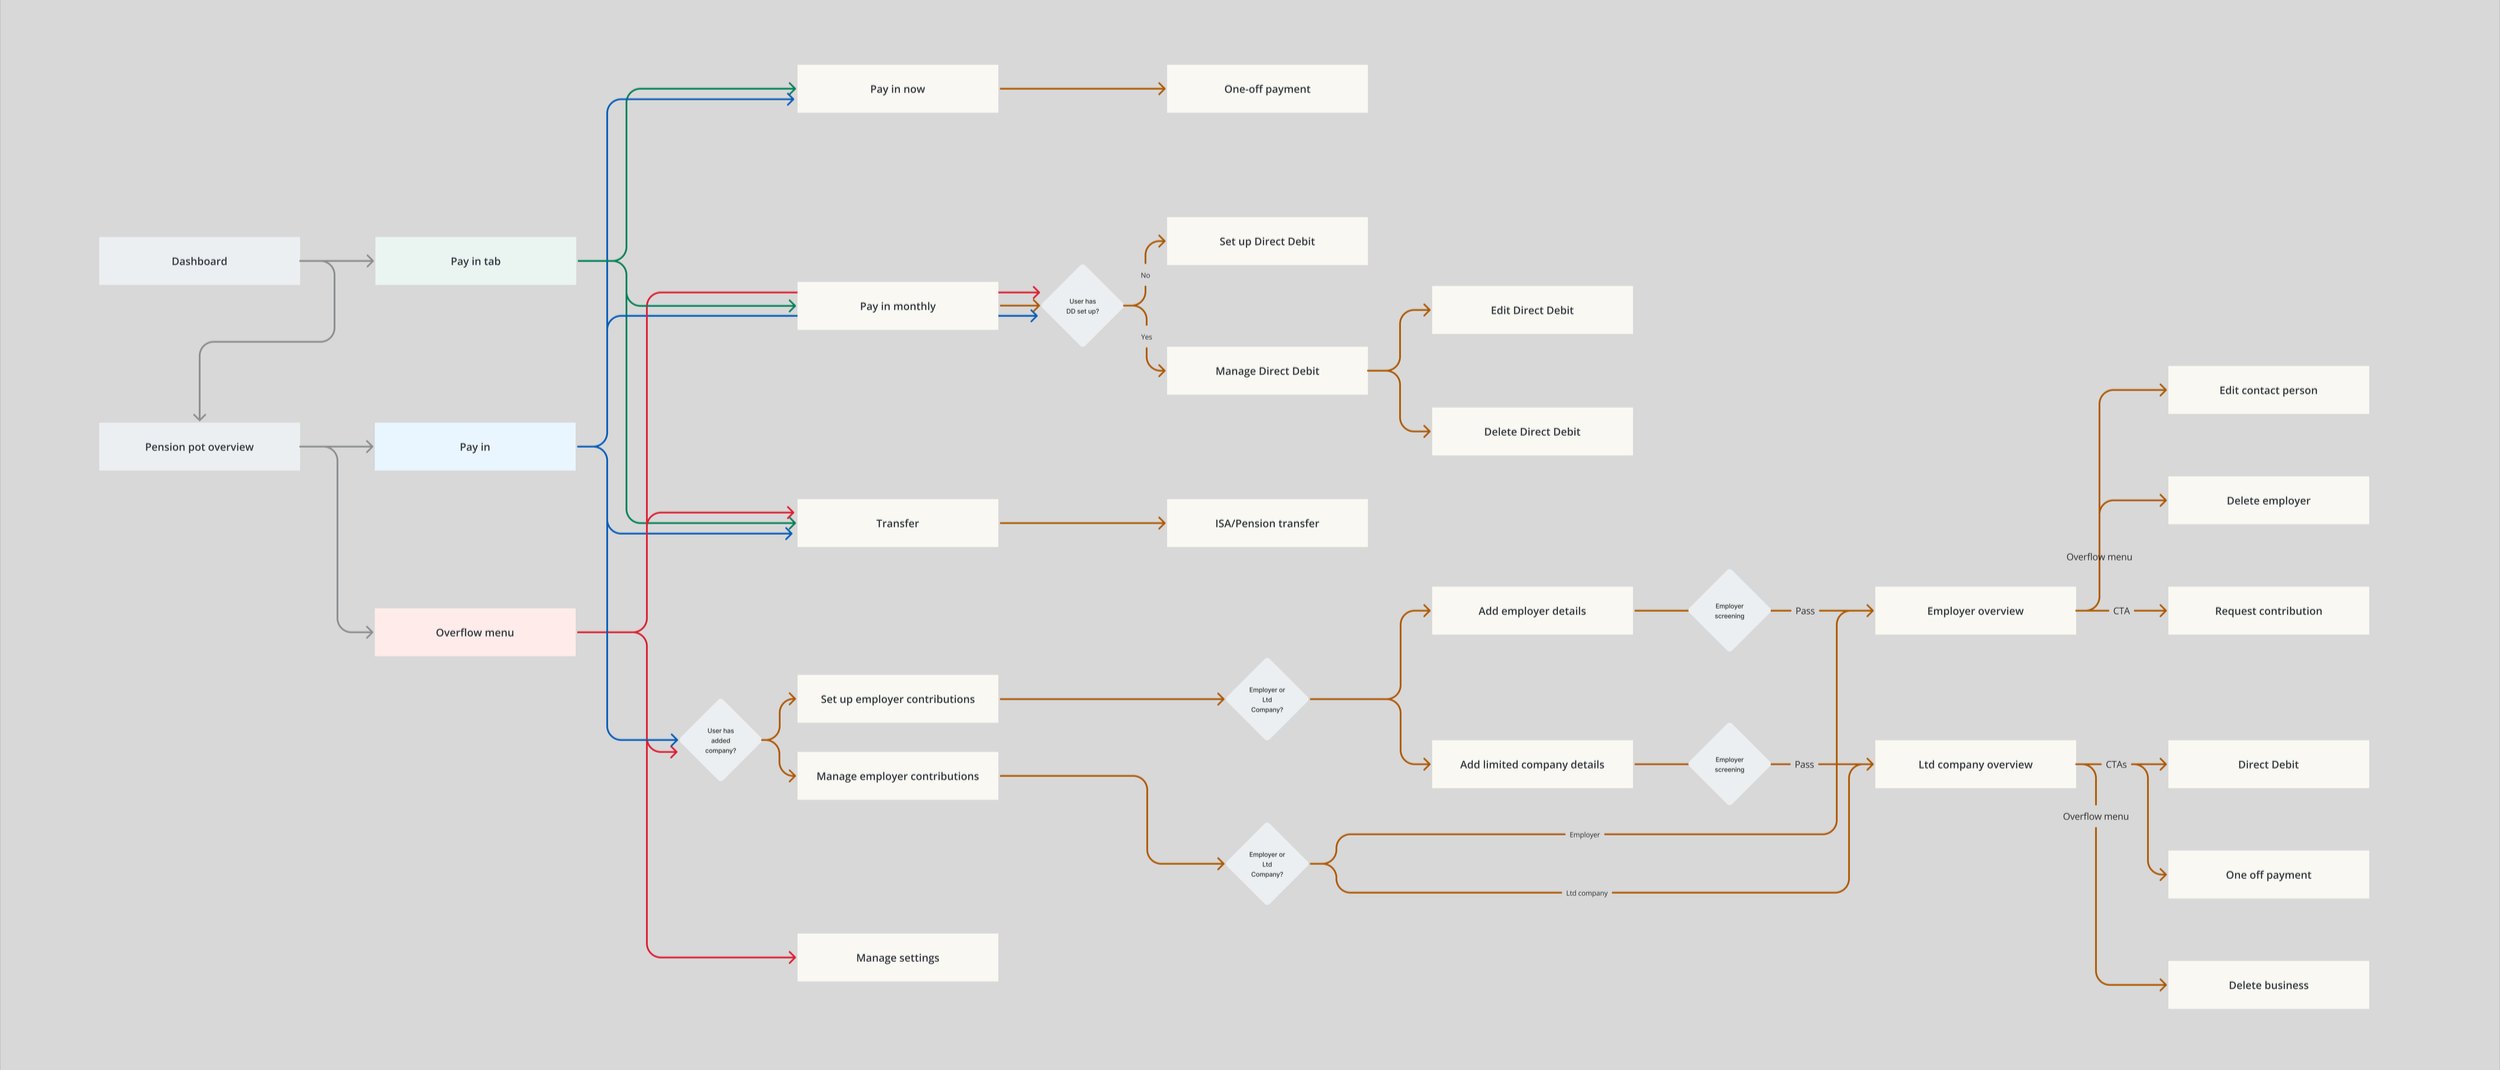
Understanding how this new journey fit into the wider payments experience
DESIGN
Making contributions faster and more self-serve
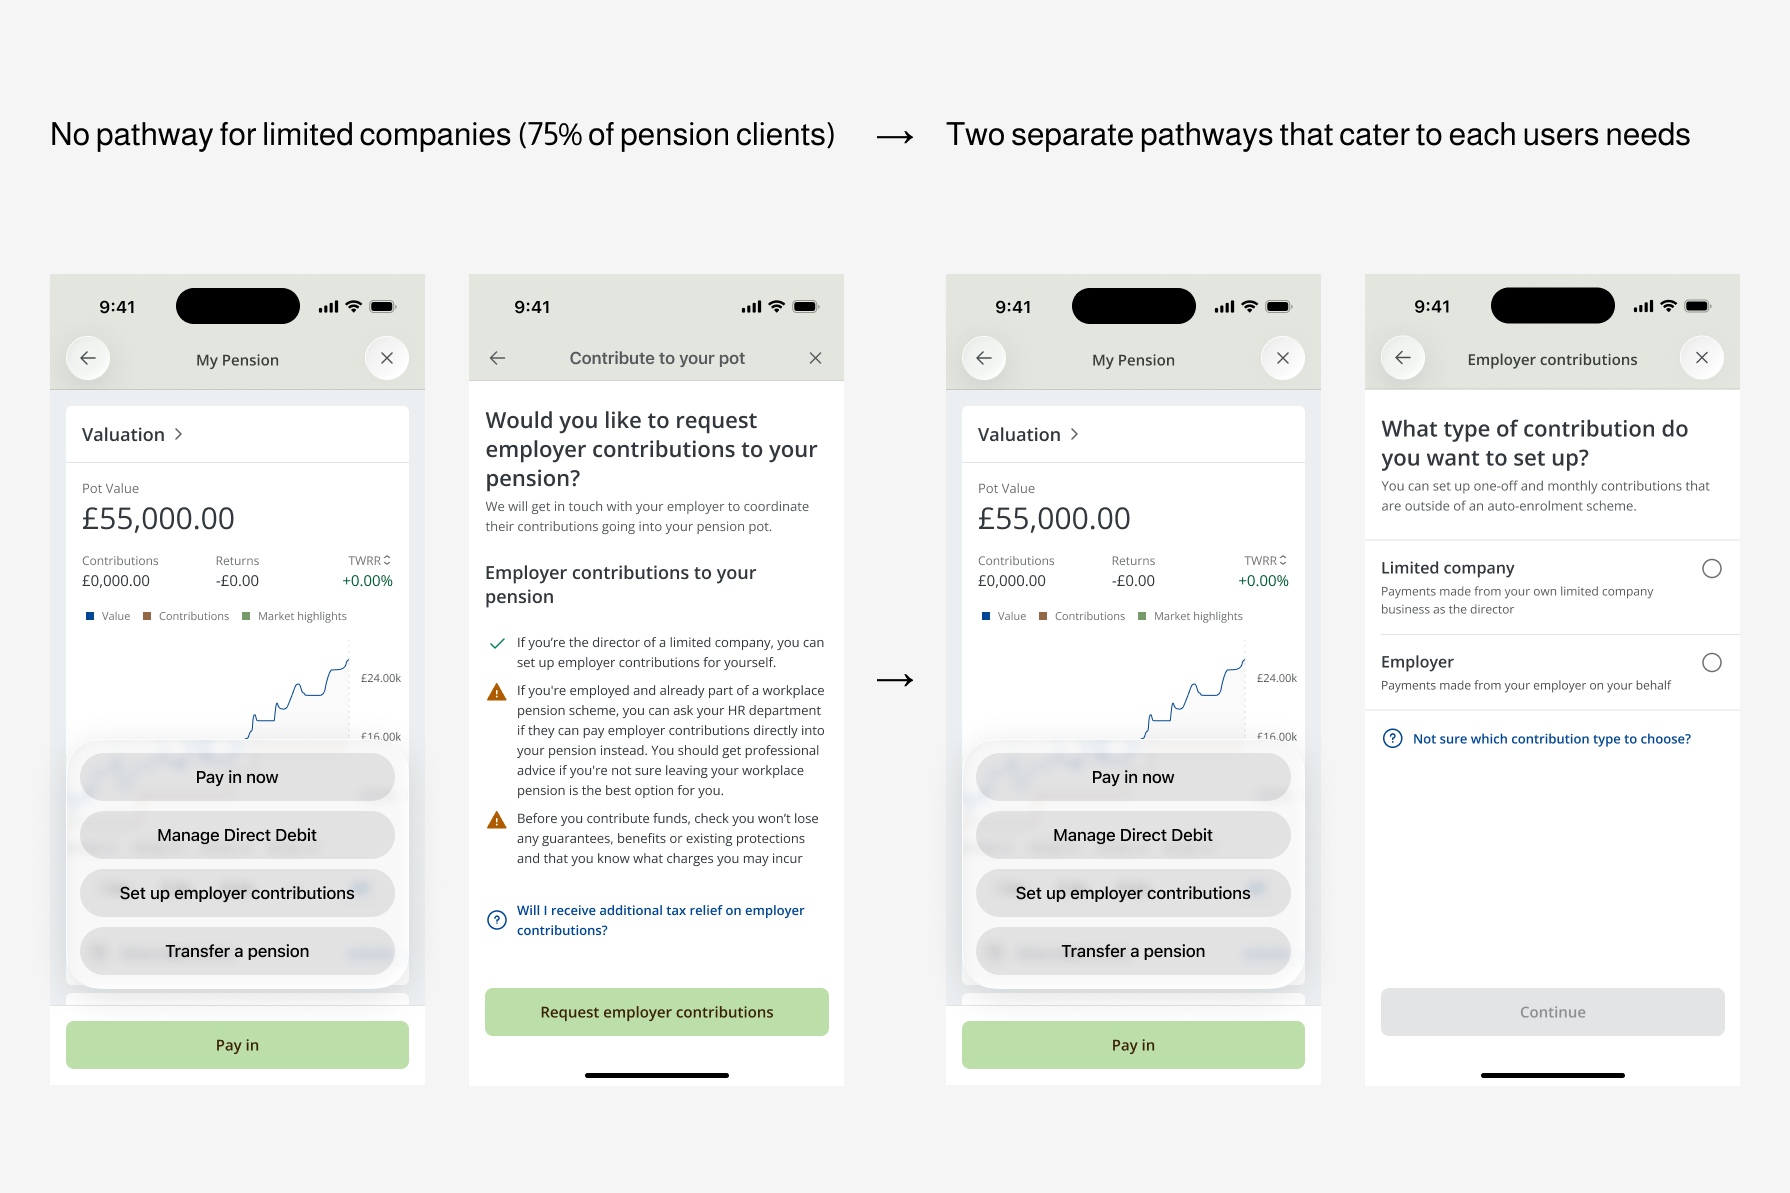
I designed two end-to-end journeys that addressed identified user challenges and catered to each of our pension client groups:
A pathway tailored to limited company directors (who control their own business bank accounts) making contributions to their personal pensions
An improved journey for other clients who want to request pension contributions from their employers
User challenge → Design solution
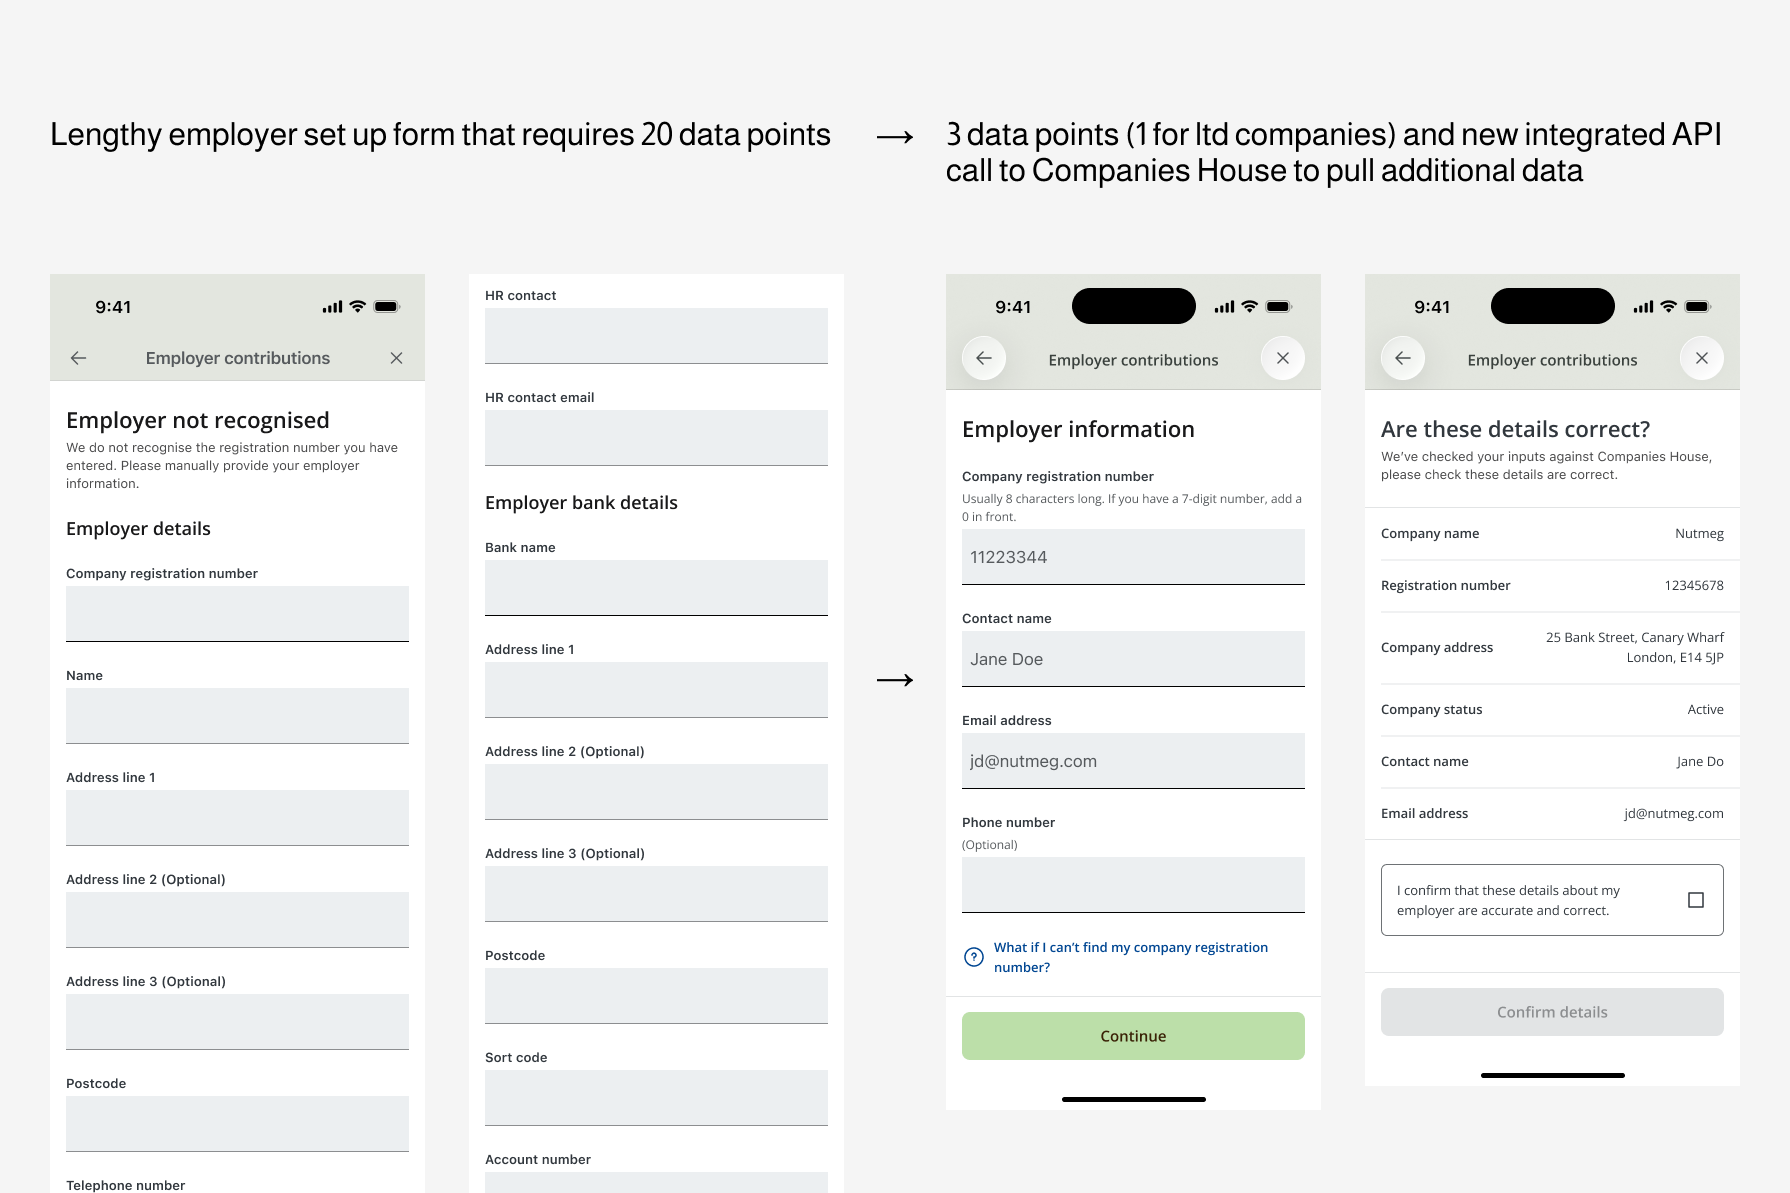
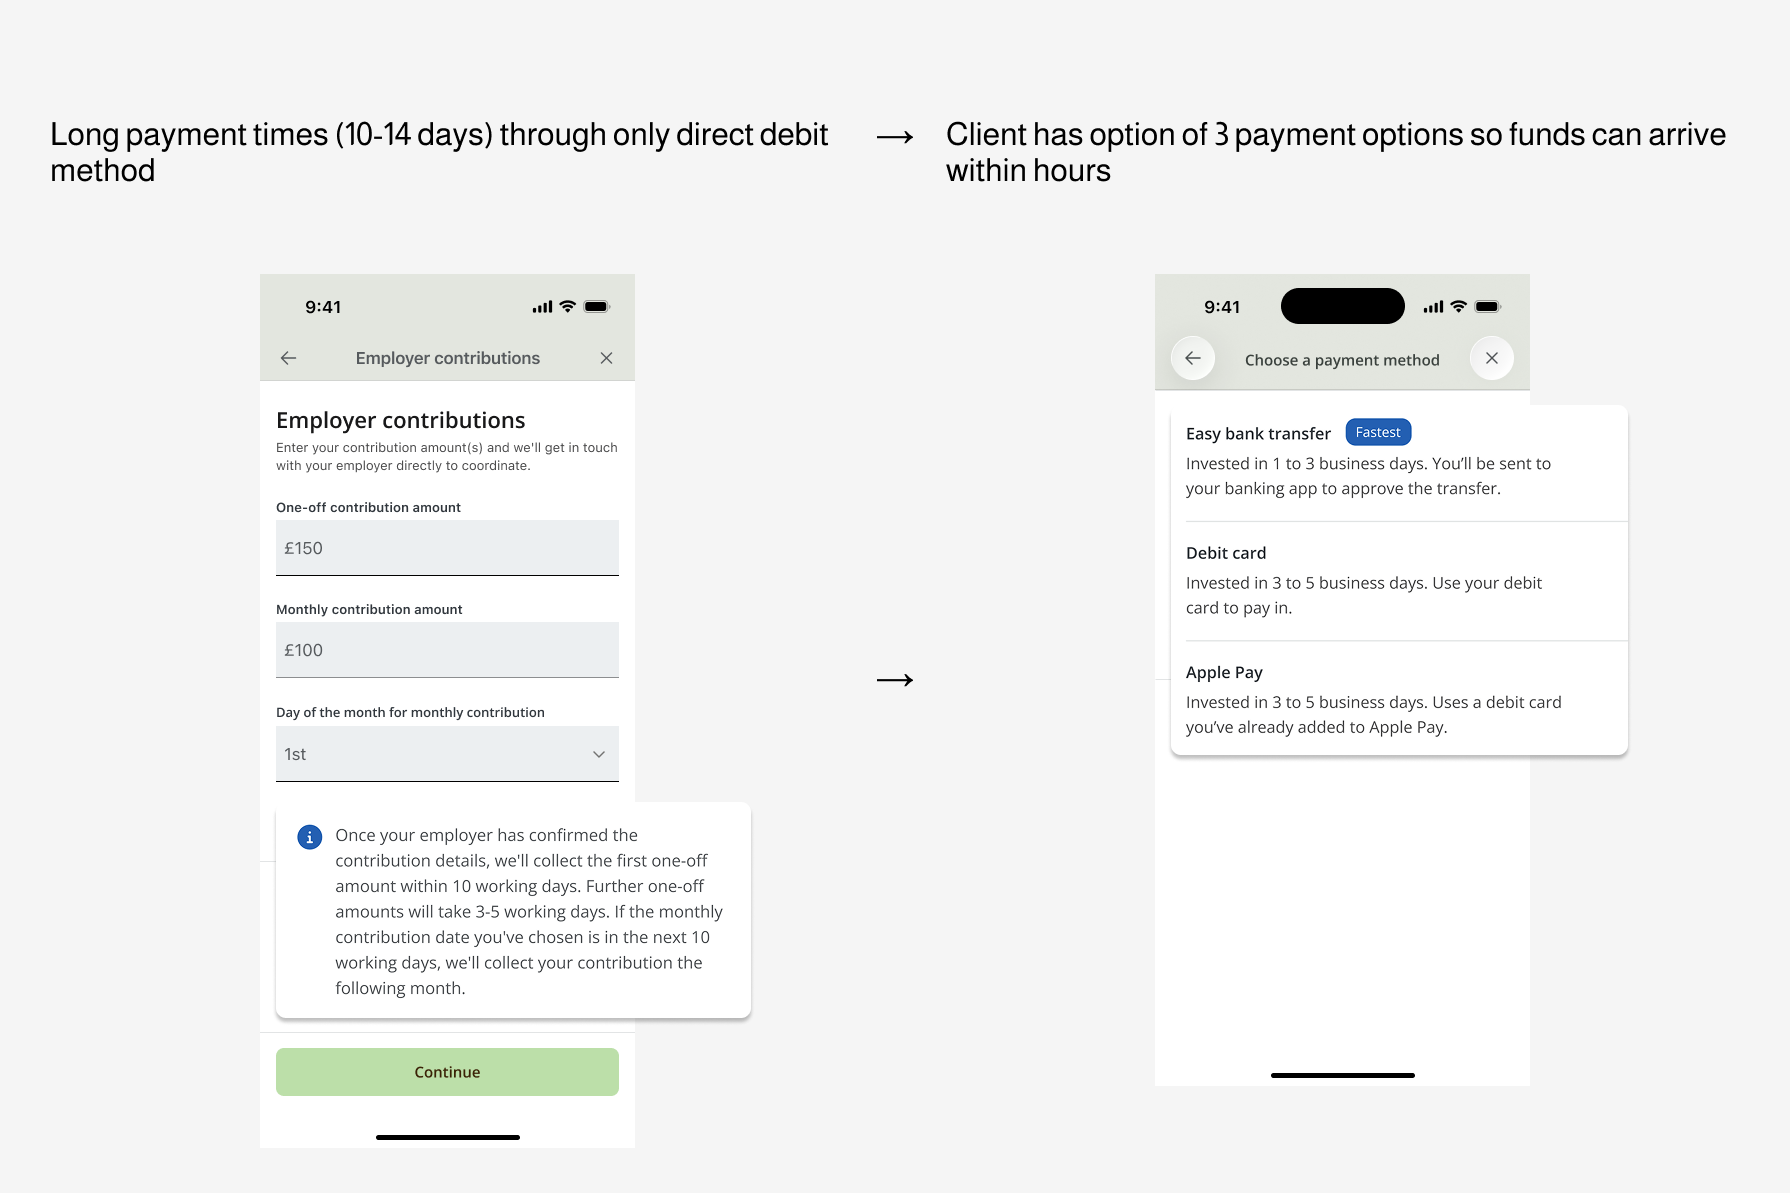
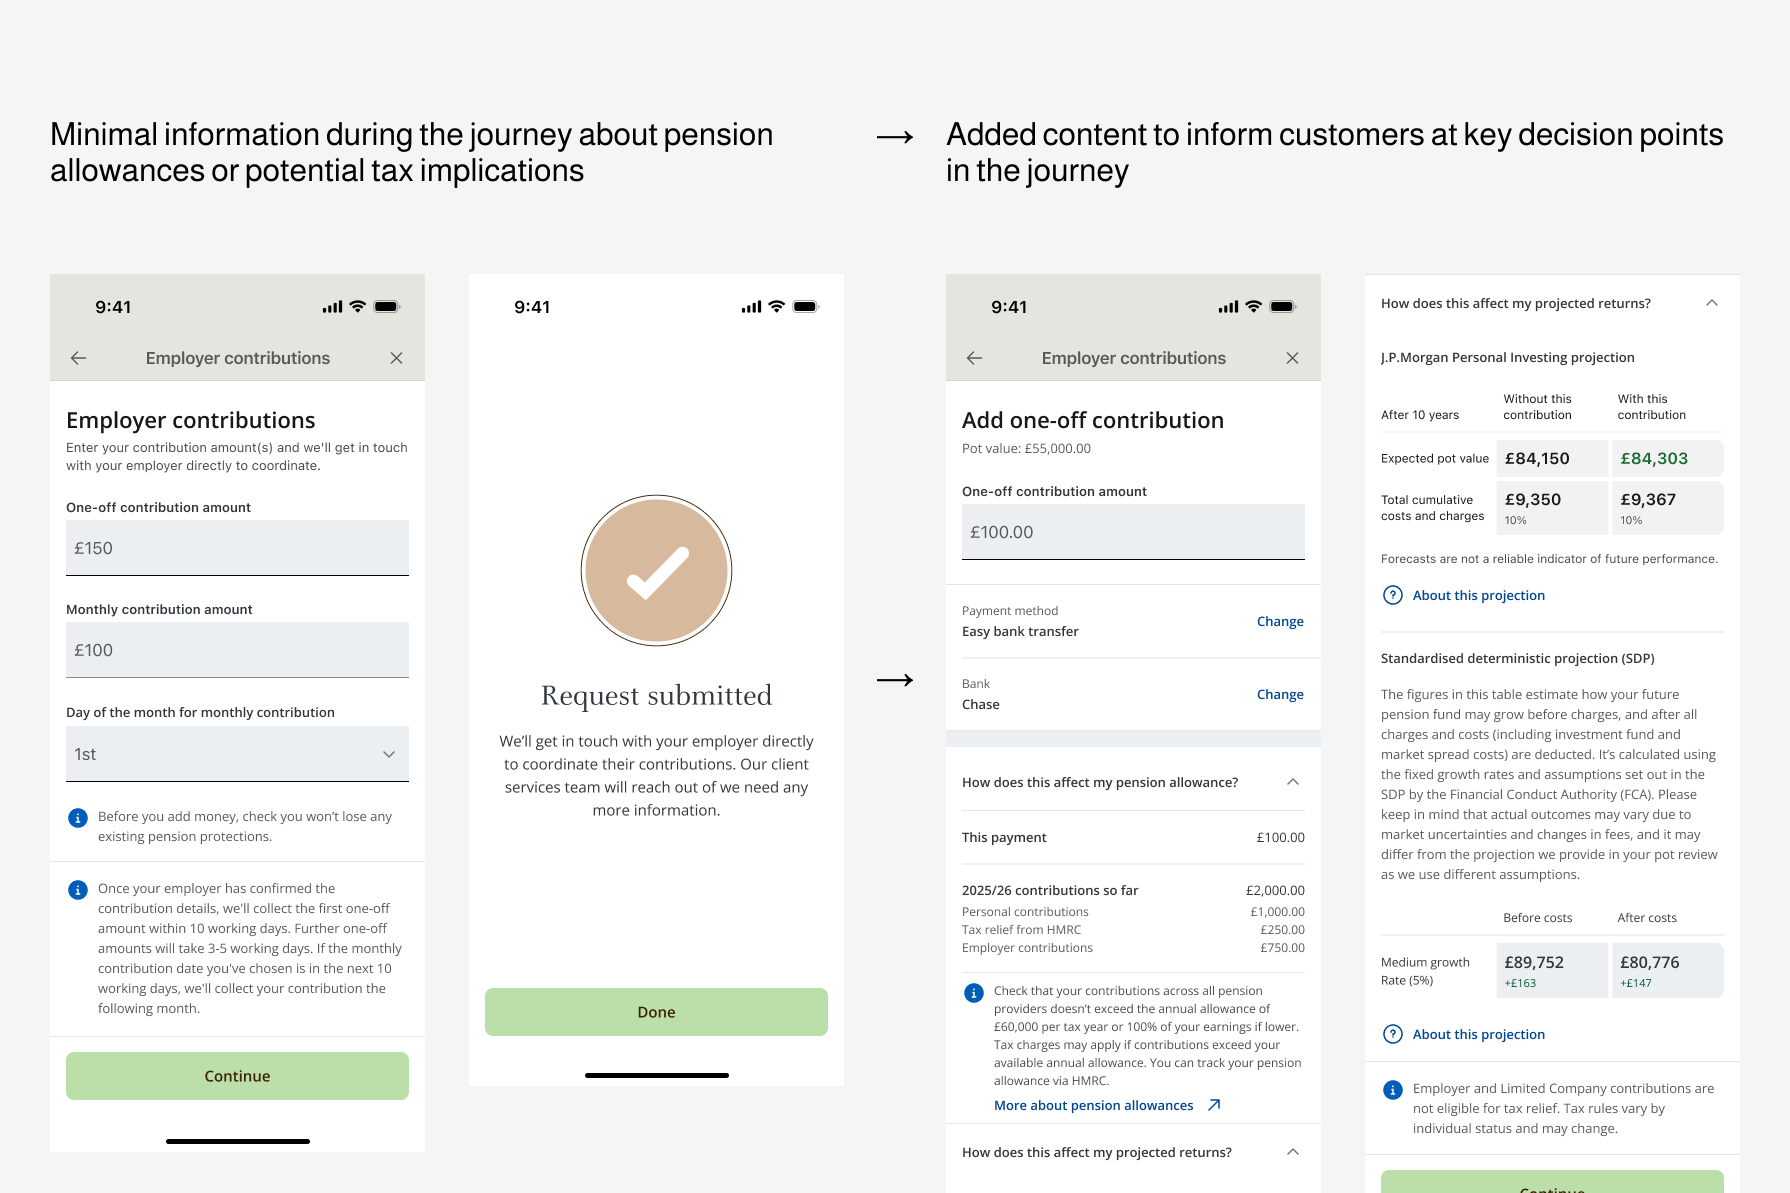
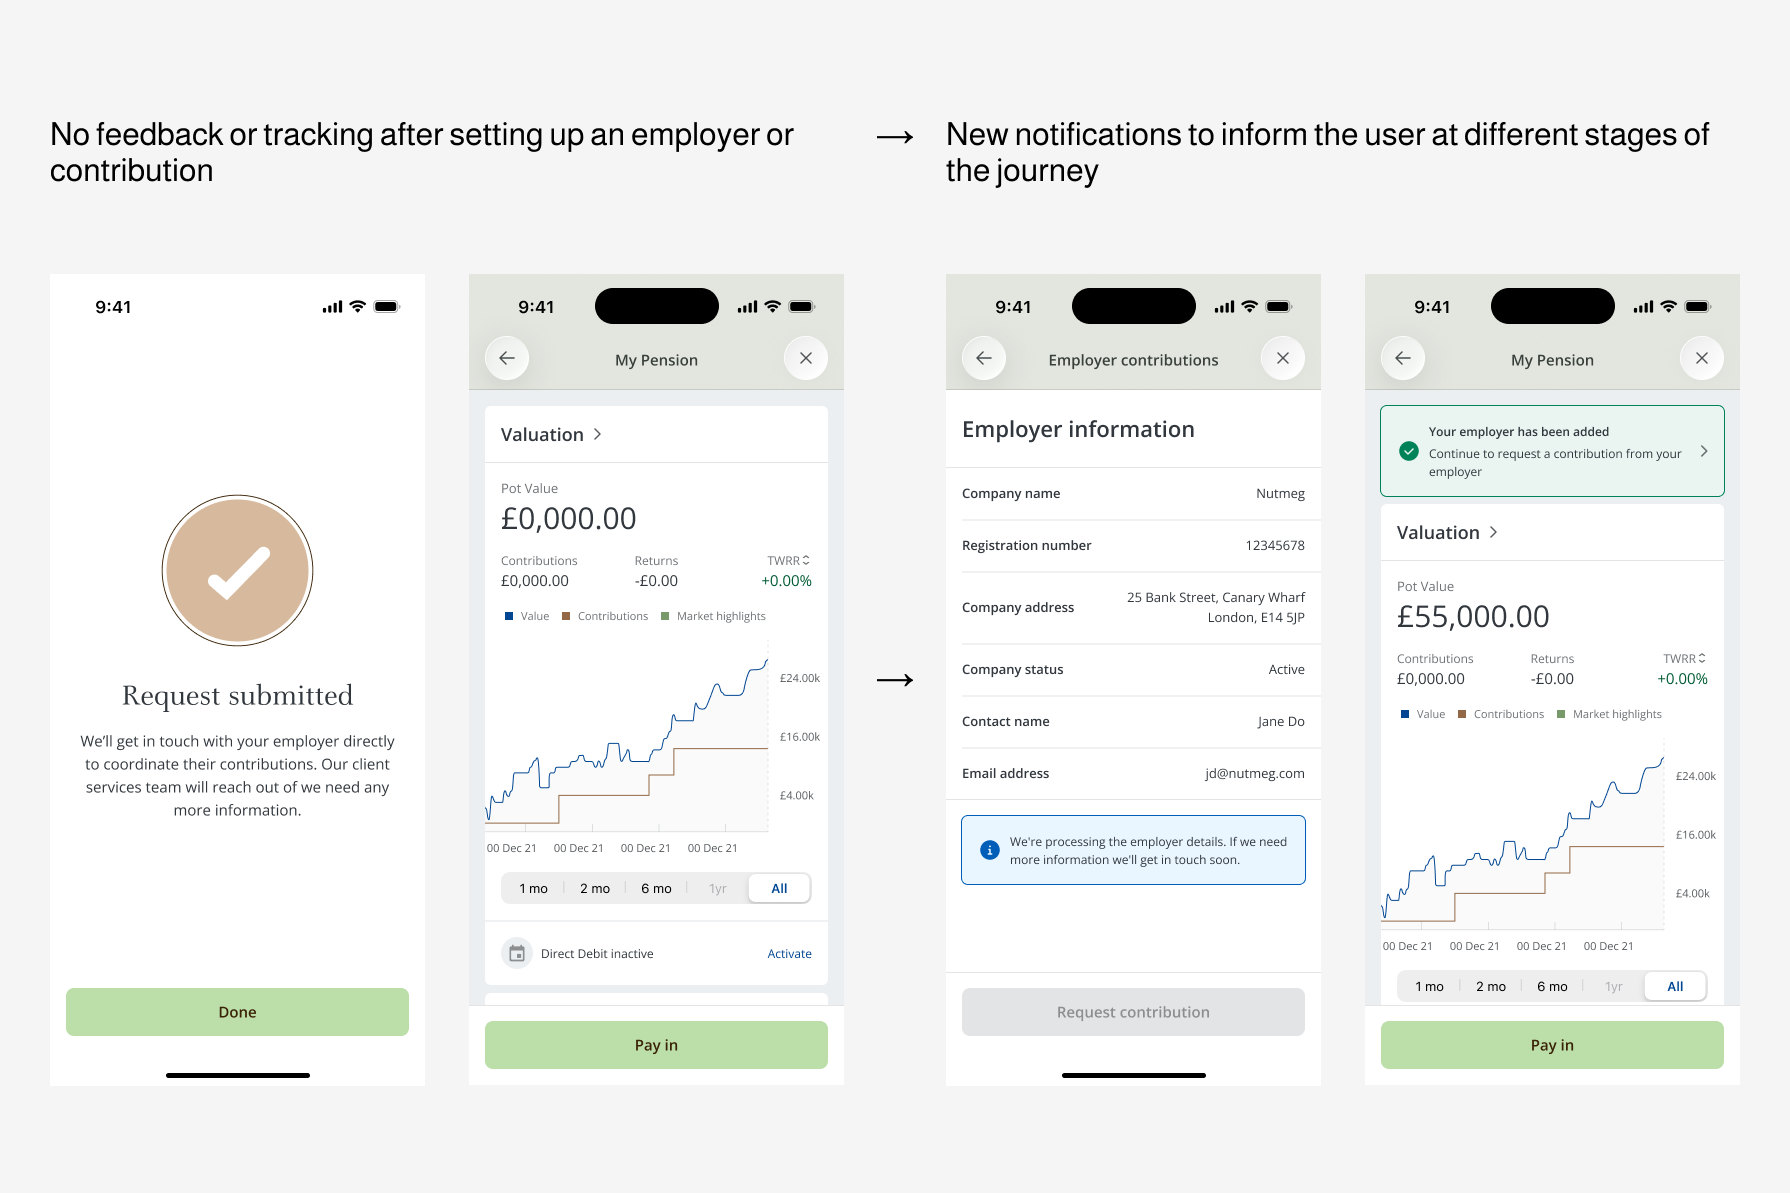
DELIVERY & IMPACT
Delivering a more focused contribution experience
Throughout delivery, I worked closely with Product to review designs, incorporate feedback and make informed decisions using available data. I collaborated with Content, Accessibility and Research to refine the experience, and partnered with Engineering to align with established patterns across similar journeys. I also advocated for consistency between mobile and web.
The resulting design enabled:
Greater customer autonomy
Less unnecessary friction
Faster payments
Clearer customer understanding
A more considered experience